Pillar: Buying building land in France
France’s development tax on pools, garden sheds and conservatories: 2026 values and how to calculate it
In 2026 the French development tax (taxe d’aménagement) on a swimming pool starts from €251 per m² of basin; on an enclosed garden shed or conservatory, from €892 per m² (€1,011 in Île-de-France, the Paris region; half that within the first 100 m² of a main home). The rates of the commune (municipality) and département (county) then apply: a 32 m² basin at 3% and 2.5% comes to €442. First step: the tax office’s online simulator, with the plot’s cadastral references.
In brief
- What is taxed: an enclosed, roofed shed, conservatory or garage, on its floor area with more than 1.80 m of headroom; a pool or an outdoor parking space, on a flat value. Open terraces, pergolas and arbours are not taxed.
- Thresholds: a project of 5 m² or less is exempt, but a 4 m² shed included in the house’s building permit is taxed with it. A pool basin of 10 m² or less is not taxed while it needs no planning consent (outside protected areas). Garden sheds of 20 m² or less: exempt only where the local authority has voted it.
- 50% allowance (€446, €505 in Île-de-France, the Paris region): for the shed or conservatory of a main home as long as home and annexes stay within the first 100 m²; not for the pool or outdoor spaces.
- Return: within 90 days of completion, under “Gérer mes biens immobiliers” (manage my property) on impots.gouv.fr; up to €1,500, a single tax bill.
On this page
What is taxed, and on what basis
The development tax (taxe d’aménagement) applies to work that needs planning consent, a prior declaration (déclaration préalable) or a permit. An enclosed, roofed annex is a building, taxed on its floor area; otherwise only the installations listed in the law are taxed, each on a fixed value.
| Annex | What is taxed | 2026 value | Thresholds and exceptions |
|---|---|---|---|
| Swimming pool | The basin, in m² | €251 per m², everywhere | Basin of 10 m² or less: no tax, except in protected areas. No allowance. |
| Enclosed, roofed garden shed | Its taxable area | €892 per m², €1,011 in Île-de-France | Project of 5 m² or less: exempt. 20 m² or less: exempt if voted. |
| Enclosed conservatory (véranda) | Its taxable area | €892 or €1,011 per m² | Counts with the home for the allowance. |
| Enclosed garage | Its taxable area | €892 or €1,011 per m² | Exempt if within the building’s vertical footprint. |
| Outdoor or carport parking space | Each space | €2,928, up to €5,857 by council decision | Two-wheelers: no tax. |
| Terrace, pergola, arbour | Nothing | None | Not both enclosed and roofed. |
Values for consent granted in 2026. Protected areas: a protected heritage area, the surroundings of a listed monument, a classified site. Sources: CGI, art. 1635 quater J (pools, parking); CGI, art. 1635 quater K (higher value per parking space); BOFiP, BOI-IF-TU-10-30-10: taxable floor area; BOFiP, BOI-IF-TU-10-20-30-170: parking built into the building. Accessed 13 November 2026.
An annex is “enclosed” as soon as a door, a window, a shutter, a roller door or a removable roof closes it off; a lean-to with no front wall and no door is not. The area is measured inside the walls, leaving out parts with 1.80 m of headroom or less.
Swimming pool: €251 per m² of basin
A pool basin is not floor area: it has a value of its own, €251 per m² in 2026, in Île-de-France as elsewhere, covered or not. If the pool sits under an enclosure more than 1.80 m high, the surround and paving under it are added as floor area.
A basin of 10 m² or less needs no planning formality and so escapes the tax, except in a site patrimonial remarquable (protected heritage area), near a listed historic monument, or in a classified site or one being classified, where a declaration is required. The 50% allowance does not apply to a pool, even at a main home: it only covers the value of buildings.
Sources: BOFiP, BOI-IF-TU-10-30-30: pools and parking areas; Planning Code, art. R*421-2 (work needing no consent). Accessed 13 November 2026.
Sheds and conservatories: the 5 m² threshold and the first 100 m²
An enclosed, roofed garden shed or conservatory is a building: €892 per m² of taxable area outside Île-de-France, €1,011 inside it. The exemption by law covers buildings of 5 m² or less, but the threshold is judged on the whole authorised project. A 4 m² shed on its own plot is exempt; the same shed in the permit for a 120 m² house is taxed, on 124 m².
For a garden shed of 20 m² or less not used for business, the commune (municipality) or group of communes, the département (county) and the Île-de-France region may each vote a full or partial exemption, for their own share only. Ask the planning department of the mairie (town hall) for the council decisions.
The 50% allowance for a main home
The first 100 m² of a home used as a main residence, with its annexes, count at €446 (€505 in Île-de-France). When you extend, even with an annex standing apart from the house, the new area is added to the home’s: the allowance only covers what is left below 100 m². A second or holiday home gets no allowance.
Sources: BOFiP, BOI-IF-TU-10-20-30-160: buildings of 5 m² or less; CGI, art. 1635 quater E (optional exemptions); BOFiP, BOI-IF-TU-10-30-20: allowances. Accessed 13 November 2026.
Garages and parking spaces
An enclosed garage is a building, counted among the home’s annexes for the allowance. It is exempt by law if it lies above or below the building, or is built into it within its vertical footprint; detached, or attached outside the house’s footprint, it is taxed.
An outdoor space, or one under a roof that is not fully enclosed such as a carport, is taxed per space: €2,928 in 2026. The commune, or the group of communes responsible for the local plan (PLU), can raise this to €5,857 by a council decision, and the département then uses the same value. Spaces for two-wheelers are not taxed.
Sources: BOFiP, BOI-IF-TU-10-20-30-170: parking built into the building; CGI, art. 1635 quater K (higher value per parking space). Accessed 13 November 2026.
Worked example: a pool and a shed in one declaration
Assumptions: a 120 m² main home outside Île-de-France, an 8 × 4 m pool and a 12 m² shed in one prior declaration cleared in 2026, no exemption voted. Example rates from Service-Public, the official information site: 3% for the commune, 2.5% for the département.
- Value: 32 m² × €251 = €8,032 for the pool, plus 12 m² × €892 = €10,704 for the shed, with no allowance as the house is over 100 m²; total €18,736.
- Shares: €562.08 for the commune, €468.40 for the département.
- Tax due, rounded to the nearest euro: €1,030, on a single bill as it does not exceed €1,500.
- If the work affects the subsoil, the archaeology tax (taxe d’archéologie préventive) adds 0.40% of the same value: €75, on a separate bill.
| Project (outside Île-de-France) | Taxable value | Commune 3% | Département 2.5% | Tax due |
|---|---|---|---|---|
| Pool, 8 × 4 m basin | 32 × €251 = €8,032 | €240.96 | €200.80 | €442 |
| 12 m² shed, 120 m² house | 12 × €892 = €10,704 | €321.12 | €267.60 | €589 |
| 12 m² shed, 80 m² house | 12 × €446 = €5,352 | €160.56 | €133.80 | €294 |
| 18 m² conservatory, 120 m² house | 18 × €892 = €16,056 | €481.68 | €401.40 | €883 |
| One outdoor space | €2,928 | €87.84 | €73.20 | €161 |
| One space, highest value | €5,857 | €175.71 | €146.43 | €322 |
Calculated by TerrainCheck, each annex on its own, houses used as main homes; tax rounded to the nearest euro. 2026 values, example rates. Sources: CGI, art. 1724 (rounding to the euro); CGI, art. 1679 octies (tax bills); CGI, art. 235 ter ZG (archaeology tax). Accessed 13 November 2026.
Costing, applying, filing: the steps
- Measure from the plans the taxable area, the basin, the outdoor spaces and the existing home. Cost: none. Time: about an hour (TerrainCheck estimate).
- Run the planning-tax simulator on impots.gouv.fr (in French): postcode, cadastral references, total area after the work, existing rooms included. It uses the latest rates in force, which may not be those of the year of your consent. Cost: none. Result on screen.
- Ask the mairie for the council decisions in force: the rate and the plot’s sector, the parking value, any shed exemption. Cost: none. Ask for the rate decision, or the answer, in writing.
- File the prior declaration or the permit at the mairie. Standard processing time from receipt of a complete file: one month for a prior declaration, two months for a permit for a single-family house or its annexes, extended in the cases listed in the code (by one month near a listed monument, for example). Cost: plans at your expense, on a quote if a professional draws them.
- File the return after completion, within 90 days, in your secure account on impots.gouv.fr under “Gérer mes biens immobiliers”, or on a paper form sent to the land tax office (centre des impôts fonciers). Cost: none. When the bills arrive is covered in our guide to calculating and paying the development tax.
The amount varies mainly with Île-de-France (€1,011 per m² and a regional share of up to 1%), council decisions and the rates: département 2.5% at most, commune 1% to 5%, but up to 20% in sectors where a reasoned council decision has set it because new building there calls for major road, network, restructuring or urban renewal works, or public facilities. At 20% + 2.5%, the example above goes from €1,030 to €4,216. For a shed on land where building is not allowed, see sheds and cabins on agricultural land.
Sources: Planning Code, art. R*423-19, R*423-23 and R423-24 (processing times); CGI, art. 1635 quater P (return); CGI, art. 1635 quater F (taxable event); CGI, art. 1635 quater L (rates, sectors); CGI, art. 1635 quater M (rate ceilings); CGI, art. 1635 quater N (higher rate of up to 20%); Service-Public: taxe d’aménagement (TA). Accessed 13 November 2026.
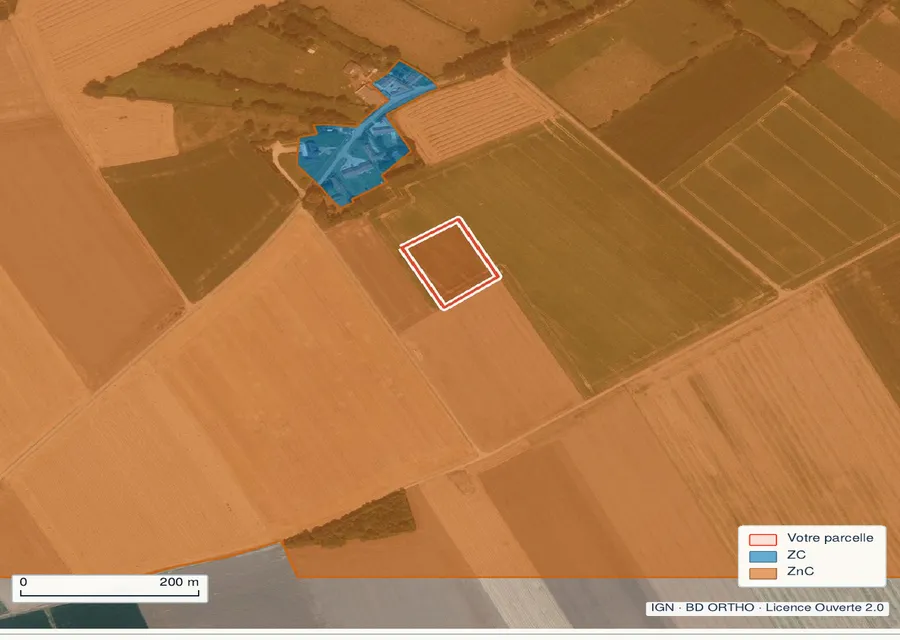
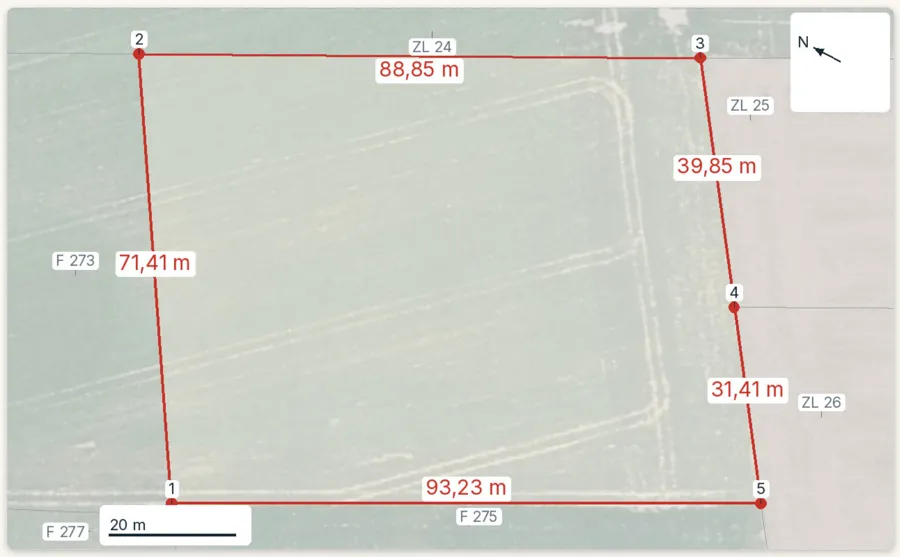
In the report: public easements around the plot
Before you file
- Each annex sorted: enclosed and roofed, pool, outdoor space, or none of these.
- Taxable area measured inside the walls, parts under 1.80 m left out.
- Floor area of the existing home noted, to see what is left of the first 100 m².
- Rate sector, parking value and shed exemption asked at the mairie.
- Plot checked for a protected heritage area, a listed monument nearby or a classified site.
- Money set aside for after completion, archaeology tax included if the subsoil is affected.
Common questions
Is an above-ground pool subject to the development tax?
Yes if it needs planning consent: the tax is based on the basin area, €251 per m² in 2026, whether the pool is sunk or above ground. A basin of 10 m² or less needs no formality and so no tax, except in a protected heritage area, near a listed monument or in a classified site.
Is a garden shed under 20 m² exempt?
Not automatically. The exemption by law stops at 5 m² for the whole project. Between the two, the commune, the département and, in Île-de-France, the region may each exempt non-business garden sheds of 20 m² or less for their own share: check their council decisions.
Does a second home get the 50% allowance on a conservatory?
No. The allowance on the first 100 m² is reserved for a main home and its annexes, so a conservatory added to a holiday home is taxed at the full €892 per m² (€1,011 in Île-de-France).
Keep reading
France’s development tax (taxe d’aménagement): how it is calculated, when it is due and who is exempt
Sheds, cabins and mobile homes on agricultural or natural land in France: what is allowed
Dividing a plot in France: prior declaration, development permit or nothing, depending on the case
Before you add a pool or a shed, look at the land
Pick the parcel on the map. The report brings together its planning zone, natural hazards, dimensions and the land sales recorded nearby (except in Alsace, Moselle and Mayotte), each with its source and date, explained in English. It does not calculate the development tax. Free preview, PDF report for €29 (€39 in French and English).
